Allow for tax at checkout when the displayed price excludes it. In Pigeon Forge, ordinary shopping, qualifying groceries and purchases with a city add-on have different tax treatments. Dollywood admission carries both sales tax and amusement tax, while prepared meals and short accommodation stays have their own city charges.
Tax on shopping, groceries, meals, rooms and tickets
| Purchase | Sales tax | City add-on | Published combined rate |
|---|---|---|---|
| Ordinary shopping | 7% state + 2.75% local | None | 9.75% |
| Qualifying groceries | 4% state + applicable local | None | — |
| Prepared meals | General sales tax | 1% restaurant tax | — |
| Short-stay lodging | General sales tax | 2.5% lodging tax | 12.25% |
| Standard Dollywood admission | 9.75% sales tax | 2.5% amusement tax | — |
The general sales-tax rate already combines state and local tax. The table applies to purchases within Pigeon Forge city limits. A category-specific city tax is an additional charge, not another name for the local portion.
Qualifying food and food ingredients are substances sold for human ingestion or chewing, consumed for taste or nutritional value, whether liquid, solid, frozen, dried, dehydrated or concentrated. Candy, dietary supplements, prepared food, alcohol and tobacco do not qualify for grocery treatment. Prepared food includes items heated by the seller, ingredients mixed by the seller into one item, or food sold with eating utensils.
The restaurant add-on applies to the consideration charged for prepared food at restaurants, cafés, caterers, delicatessens, snack bars and similar sellers. Takeaway food is covered too. Alcohol is excluded from this add-on. Exceptions cover food prepared for churches, schools, senior citizen centres and nursing homes, and boarding-house food included in rent.
The lodging add-on is calculated on gross hotel sales. It covers paid occupancy in hotels, inns, motels, tourist camps, cabins and similar accommodation for stays of less than 90 continuous days. Longer continuous stays are exempt from lodging sales tax, and complimentary accommodation with no payment received is outside the city tax.
The amusement charge covers paid admission, including season tickets, subscriptions, additional admission within an enclosure and charged recreational facilities or equipment. Shows, theme parks, museums, water attractions and paid games fall within its scope. Wholly complimentary activities with no consideration received are excluded. For each admission ticket, a fractional cent of amusement tax is rounded up to the next cent.
From the advertised price to the final bill
Do
- Use a stated tax-inclusive total as your starting point.
- Add the relevant tax to a tax-exclusive price.
- Separate statutory taxes, mandatory seller fees, optional extras and refundable deposits on the itemised bill.
Don’t
- Add tax again to a total that already includes it.
- Treat every checkout surcharge as a government tax.
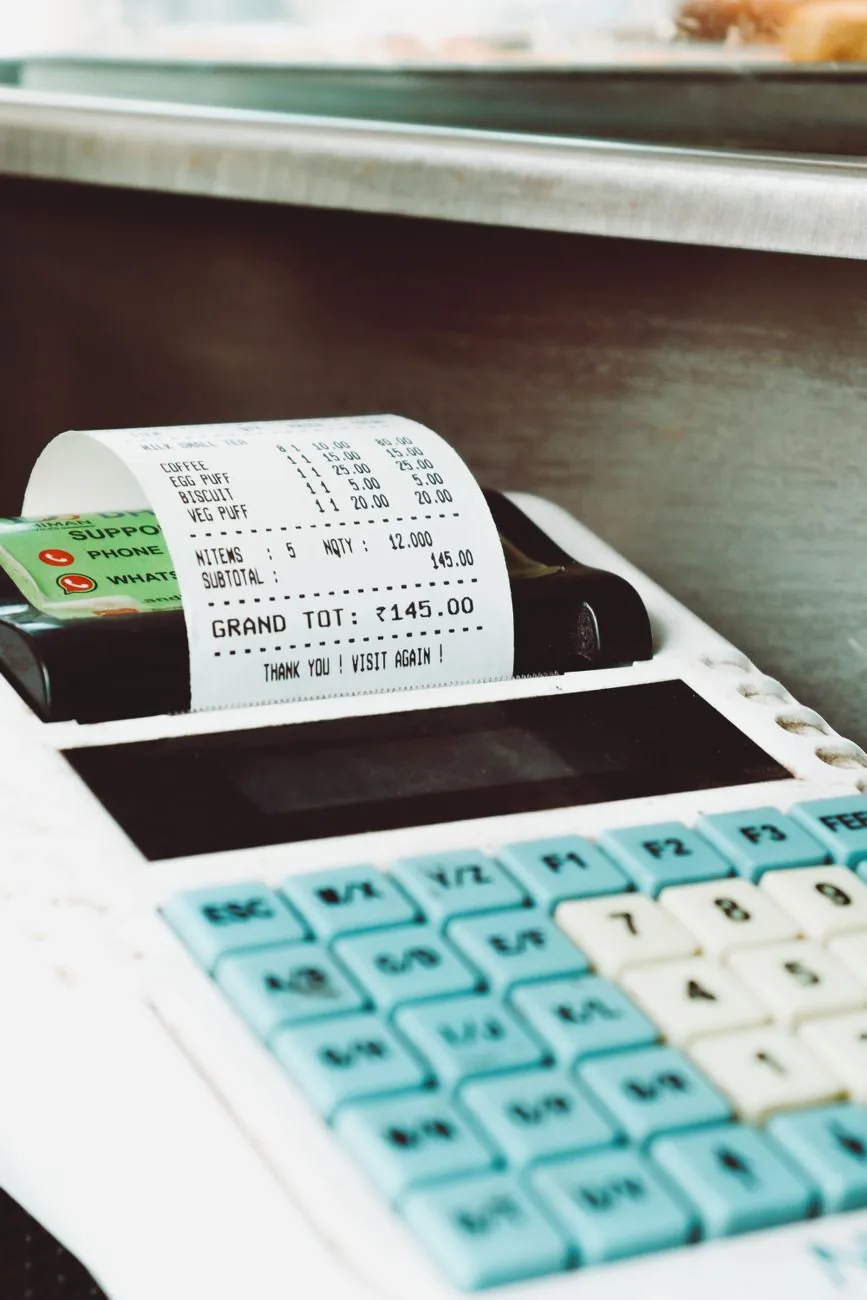
For a hypothetical ordinary retail purchase priced at $40 before tax, the tax is $3.90 and the total is $43.90, assuming no other charges. Apply the purchase category’s treatment to the taxable subtotal, rather than treating every line on the bill alike.
Mandatory or routinely charged accommodation cleaning fees are subject to sales tax as part of the lodging charge. A separate fee triggered only by abnormal circumstances, such as breaking a no-smoking rule, is not taxable. A refundable deposit and an optional extra should remain identifiable rather than being folded into a line labelled tax.
GOWTHAM AGM · Pexels License · Edited
For an in-person Tennessee purchase, the local jurisdiction is generally the seller’s business location where the sale takes place. A Pigeon Forge mailing address alone does not determine which local rate applies.
Visitor exemptions and the tax-free weekend
| Holiday category | Qualifying examples | Per-item ceiling |
|---|---|---|
| Clothing | Ordinary clothing and footwear | $100 |
| School and school art supplies | Notebooks, pencils, paints, sketch pads | $100 |
| Computers | Desktops, laptops, tablets | $1,500 |
Living outside Tennessee does not exempt an ordinary visitor from sales tax. International tourists also have no general refund for taking purchases home. The tax-free weekend is a lawful way to avoid sales tax on eligible goods, provided they are for personal use, not business, trade or rental.
Each year, the holiday runs from 12:01am on the last Friday in July through 11:59pm the following Sunday. It also applies to online purchases. Restaurant meals, accommodation and amusement admissions are outside the holiday.
Clothing accessories, protective equipment and specialist sports equipment remain taxable, including cleated shoes and ski boots. School instructional materials and school computer supplies are excluded. Over-limit school supplies and computers are taxed on their full price, not just the excess.
A computer CPU can qualify separately, but other components must be bundled with the computer. Separately sold monitors, keyboards, software and storage media do not qualify, nor do e-readers, games consoles or printers. Store discounts reduce the qualifying price, but third-party-reimbursed rebates do not. Extended warranties remain taxable.
Eligible organisations need a current Tennessee Certificate of Exemption or a completed Streamlined Sales Tax Certificate with their Tennessee exemption number. An out-of-state 501(c)(3) may instead use its federal exemption letter. The organisation must purchase directly and pay from its own funds, not reimburse a personal purchase. Cash receipts must identify it and the sale amount, while cheques or billed cards must bear its name. Tennessee does not accept other states’ nonprofit exemption certificates.
If a tax charge looks wrong
- Identify the purchase category and taxable subtotal. Separate statutory taxes from seller fees, and retain the itemised receipt.
- Ask the seller to correct the charge and refund overcollected tax. Keep written or electronic proof of your request.
- A direct Department of Revenue claim must exceed $2,500 per seller, involve tax collected and remitted by that seller, and follow its failure or refusal to refund after two documented requests. Make the second request after a written refusal or 30 days after the first request, whichever comes first.
- Request the seller’s attestation that it remitted the tax and has not claimed or taken a refund or credit. Allow 30 days for it to provide or decline the form before filing. Include the attestation and proof of both requests. If unavailable, provide enough information to verify the facts it would attest to.
The general refund deadline is three years from 31 December of the payment year. Special transaction rules may apply, and the requests and waiting periods do not extend the deadline. The Department is not required to refund tax collected in error by a seller.
Separately, before bringing a claim against the seller, give written notice and allow 60 days for a response. The notice must explain the overcollection and request a refund.
Sources & fact-checking
Checks against the sources below cover: fares and charges, as well as services.
- Other Exemptions
- Important Notice: Customer Refund Procedure
- STH-1 – Date of Sales Tax Holiday
- Sales Tax Holiday Alphabetical Directory: Tax-Free Items
- Tennessee’s Sales Tax Holiday Continues Two Decades of Savings
- STH-9 – Types of School and School Art Supplies that Qualify for Sales Tax Holiday Exemption
- STH-10 – Sales Tax Holiday – Qualifying Computers
- STH-13 – Sales Tax Holiday Does Not Apply to Computers Costing More Than $1,500
- STH-2 – Sales Tax Holiday – Qualifying Items
- Tennessee Taxation of Nonprofit Organizations (June 2025)
- SUT-29 – Online Sales by In-State Sellers
- SUT-47 – Short-Term Rentals Are Subject to Sales Tax
- Forms (License / Permits / Etc.) | Pigeon Forge, TN
- Sales and Use Tax
- Tennessee Sales Tax Jurisdictional and Tax Rate Database
- SUT-53 – Food and Food Ingredients – Definition and Tax Rate
- City of Pigeon Forge, Tennessee – Restaurant Privilege Tax
- City of Pigeon Forge — service
- City of Pigeon Forge — Amusement Tax Report
- Dollywood — fares and charges
- 21-18 – Customer Refund Procedure